Published August 31, 2026
The Move Act - What Could This Mean for Your Next Move
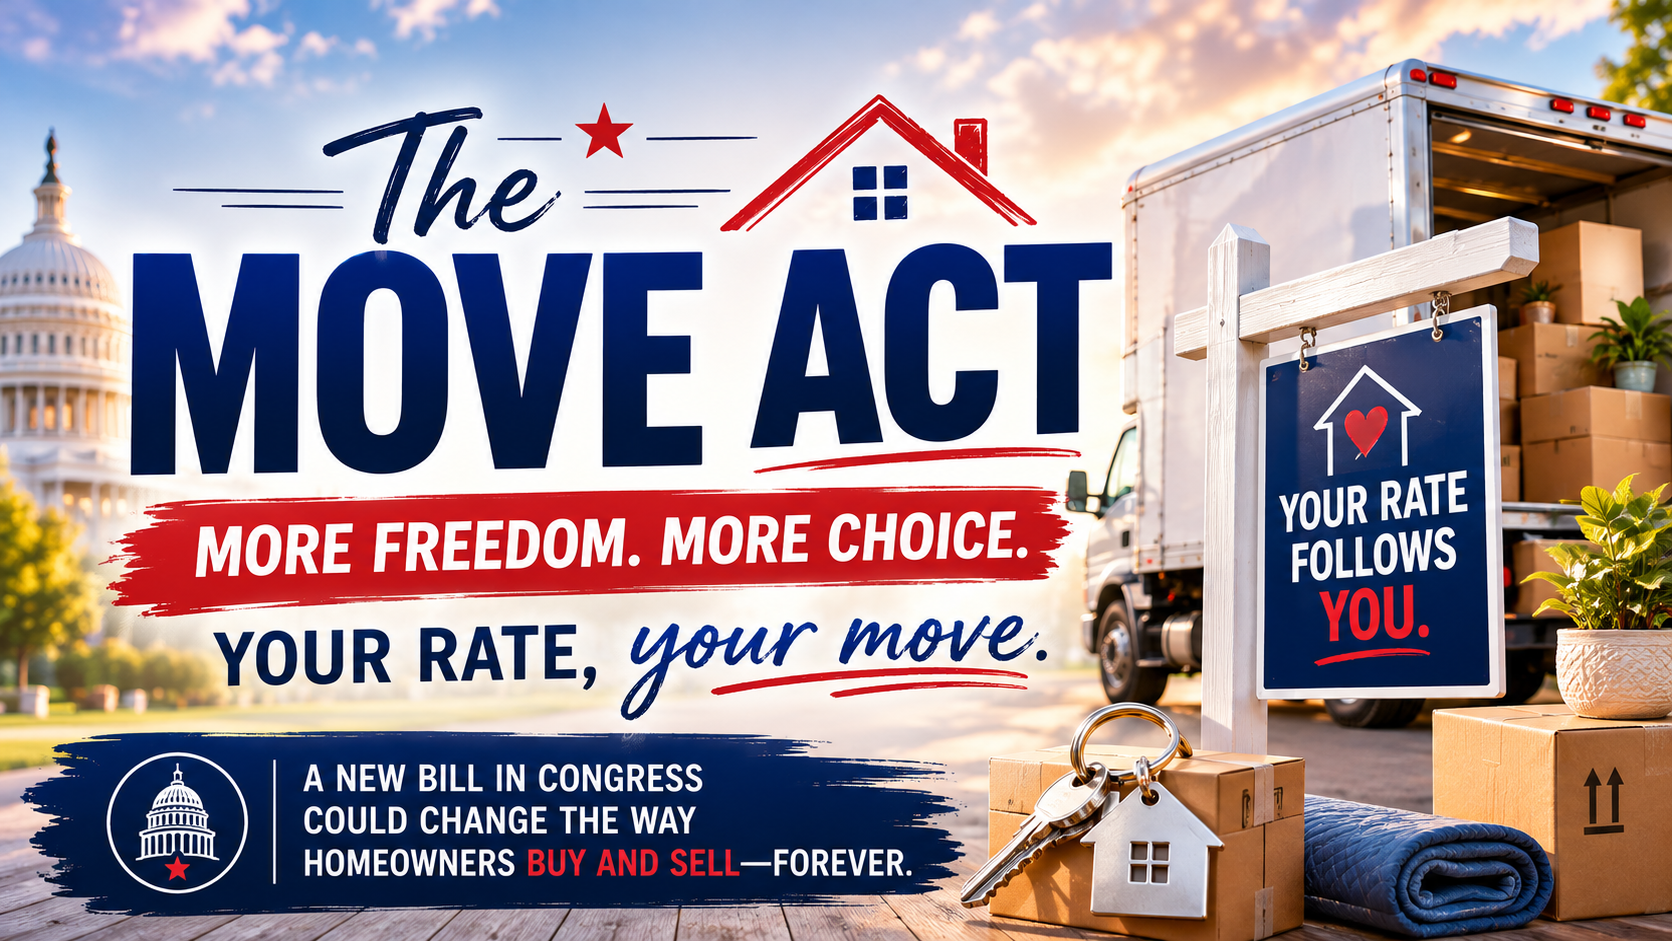
If Passed, Could the MOVE Act Let Homeowners Keep Their Low Mortgage Rates When They Move?
For many homeowners, the biggest obstacle to moving is not finding the right house, it is giving up the historically low mortgage rate they already have.
A homeowner may need more space, want to downsize or hope to move closer to family, but replacing a 3% mortgage with a significantly higher rate can dramatically increase the monthly payment. The proposed Making Ownership Viable for Everyone Act, commonly called the MOVE Act, is intended to address that problem through portable mortgages.
The concept could significantly positively affect real estate markets, including Delaware and Chester County, Pennsylvania. However, it is important to understand what the bill proposes and what it does not currently provide.
Important: The MOVE Act is proposed legislation. It has not passed Congress and is not currently available as a mortgage program.
What Is the MOVE Act?
The MOVE Act, formally introduced as H.R. 10028, was introduced in the U.S. House of Representatives on August 3, 2026, by Congressman Tom Kean Jr. of New Jersey.
If passed, the legislation would require Fannie Mae and Freddie Mac to begin purchasing and securitizing certain portable conventional mortgages within 180 days. A qualifying homeowner could potentially transfer the following to a replacement property:
- The existing interest rate
- The remaining mortgage balance
- The remaining loan terms
The transfer would need to occur within 90 days of selling the property that originally secured the mortgage. You can review the official MOVE Act legislation.
How Would a Portable Mortgage Work?
Most conventional mortgages are connected to a specific property. When that property is sold, the mortgage is paid off, and the homeowner must obtain a new loan at current interest rates.
A portable mortgage would potentially allow the homeowner to move the existing mortgage balance, rate and remaining term to another property.
This differs from an assumable mortgage:
- With an assumable mortgage, the buyer takes over the seller’s mortgage.
- With a portable mortgage, the seller takes their mortgage to their next home.
Current conventional mortgages generally include a due-on-sale provision requiring the balance to be paid when ownership transfers. The MOVE Act would attempt to create a pathway for a different type of conventional mortgage product. Review Fannie Mae’s current due-on-sale rules.
Would Your Low Rate Apply to the Entire New Home?
Not necessarily.
The proposal refers to transferring the existing mortgage balance. It would not automatically finance the entire cost of a more expensive home at the old interest rate.
For example, imagine a homeowner has:
- A $225,000 mortgage balance
- A 3.25% interest rate
- A replacement home priced at $550,000
Under a future portable-mortgage program, the homeowner might be able to transfer the $225,000 balance at 3.25%. The remaining purchase price would still need to be covered through equity, cash or additional financing.
The bill does not explain exactly how that additional financing would work. It could involve a second mortgage, a new loan at current rates or another type of blended financing. Those details would need to be established if the legislation passes.
What Could This Mean for Our Local Real Estate Market?
We regularly speak with homeowners throughout Delaware and Chester County, PA, who would consider moving if it made financial sense.
Some need another bedroom, while others want a first-floor primary suite, less maintenance or a home closer to family. Many have substantial equity but hesitate to move because they do not want to surrender a low mortgage rate.
This challenge affects homeowners throughout Wilmington, Newark, Hockessin and Middletown, as well as West Chester, Kennett Square, Downingtown, Exton and Chadds Ford.
Portable mortgages could potentially help:
- Growing families move into larger homes
- Empty nesters find smaller or lower-maintenance properties
- Seniors move closer to family
- Homeowners relocate for employment
- Owners move between Delaware and Pennsylvania
They could also encourage more homeowners to sell, potentially increasing the number of available homes for buyers.
The mortgage-rate lock-in effect is a real market issue. According to the Federal Housing Finance Agency, each percentage point by which market rates exceed a homeowner’s current rate decreases the probability of that homeowner selling by approximately 18%. Read the FHFA mortgage lock-in study.
Important Questions Remain
Although the MOVE Act has generated interest, several important details have not been determined.
Most importantly, the bill does not clearly state that existing conventional mortgages would automatically become portable. Homeowners should not assume that their current 2%, 3% or 4% mortgage would qualify if the legislation passes. The program could ultimately apply only to newly originated mortgages that include a portability feature.
Other unanswered questions include:
- Whether borrowers would need to complete a new underwriting process
- How appraisals and loan-to-value requirements would work
- How additional financing would be structured
- Whether transferring a mortgage across state lines would be permitted
- What fees lenders might charge
- Which homeowners and properties would qualify
The proposal specifically addresses eligible conventional mortgages. It does not currently establish portability for FHA, VA, USDA or jumbo mortgages.
Portable mortgages also would not eliminate other costs associated with moving, including property taxes, homeowners insurance, transfer taxes, closing costs and any applicable association fees.
What Should Homeowners Do Now?
Homeowners should not postpone an important move based solely on the possibility that the MOVE Act could become law. Its language may change, implementation could take time or the bill may not ultimately pass.
Instead, homeowners considering a move should:
- Determine their property’s current value and estimated sale proceeds.
- Confirm their mortgage balance, interest rate and remaining term.
- Estimate the payment on the desired replacement home.
- Explore using existing equity to reduce the next mortgage.
- Ask a qualified lender about recasting, bridge financing, home-equity options and assumable mortgages.
- Compare the financial cost of moving with the personal cost of remaining in a home that no longer fits.
The Bottom Line
The MOVE Act is an interesting proposal that could eventually give homeowners more freedom to move without completely surrendering a valuable low mortgage rate. It could also help unlock additional housing inventory in Delaware and Chester County, Pennsylvania.
However, as of August 2026, the bill has only been introduced and referred to the House Committee on Financial Services. It has not passed the House or Senate, has not been signed into law and does not currently allow homeowners to transfer their mortgages.
We will continue following the legislation and explaining what it could mean for local homeowners. If you are considering buying or selling a home in Delaware or Chester County, PA, The Terranova Real Estate Team can help you evaluate your equity, projected payment and options based on today’s market.